Mastering Liability Coverage: Safeguarding Your Future in 2026
In an increasingly litigious world, understanding and securing adequate liability coverage essentials is not just a recommendation; it’s a critical component of sound financial planning and asset protection. As we navigate through 2026, the complexities of personal and professional risks continue to evolve, making comprehensive liability insurance more vital than ever. This guide aims to demystify the intricacies of liability coverage, providing you with the knowledge to make informed decisions and safeguard your future.
Whether you’re a homeowner, a business owner, a professional, or simply an individual seeking peace of mind, the potential for unforeseen events leading to financial claims against you is a constant reality. From accidental injuries on your property to professional errors, or even a simple car accident, the financial ramifications can be devastating without the right protection. Our focus on liability coverage essentials will equip you with a foundational understanding of what it is, why it’s indispensable, and how to tailor it to your specific needs.
The landscape of legal liabilities is ever-changing, influenced by new regulations, societal expectations, and technological advancements. What might have been sufficient coverage a few years ago might leave you vulnerable today. Therefore, a proactive approach to reviewing and updating your liability policies is paramount. This article will delve into the various facets of liability insurance, offering practical advice and strategic insights to ensure your assets are well-protected against potential claims in the coming year and beyond.
What Exactly is Liability Coverage?
At its core, liability coverage is a form of insurance that protects you from financial losses if you are found legally responsible for causing harm to another person or damage to their property. This harm could be physical injury, property damage, or even non-physical damages like reputational harm. When a claim is made against you, your liability insurance policy is designed to cover the costs associated with your legal defense and any damages awarded, up to your policy’s limits. Without adequate liability coverage essentials, these costs would fall squarely on your shoulders, potentially leading to significant financial strain or even bankruptcy.
Understanding the fundamental principle of liability is key. It’s about responsibility and accountability. If your actions, or in some cases, your inactions, lead to a third party suffering a loss, you could be held liable. This can arise from a myriad of situations: a visitor slipping on your icy driveway, an employee injuring themselves at your business, a professional giving incorrect advice, or even your dog biting someone. The scope of potential liabilities is vast, highlighting the universal need for this type of protection.
The primary purpose of liability insurance is to shield your assets – your home, savings, investments, and future earnings – from being used to satisfy judgments or settlements. It acts as a financial buffer, ensuring that a single unfortunate event doesn’t derail your entire financial stability. As we explore the different types of liability coverage, you’ll see how this fundamental principle applies across various aspects of your life and business, making liability coverage essentials a cornerstone of robust financial planning.
The Different Facets of Liability Coverage: A Comprehensive Overview
Liability coverage essentials aren’t a one-size-fits-all solution; they encompass a variety of policy types, each designed to address specific risk profiles. Recognizing the distinctions between these types is crucial for building a comprehensive protection strategy. Let’s break down the most common forms of liability coverage you’ll encounter.
Personal Liability Insurance
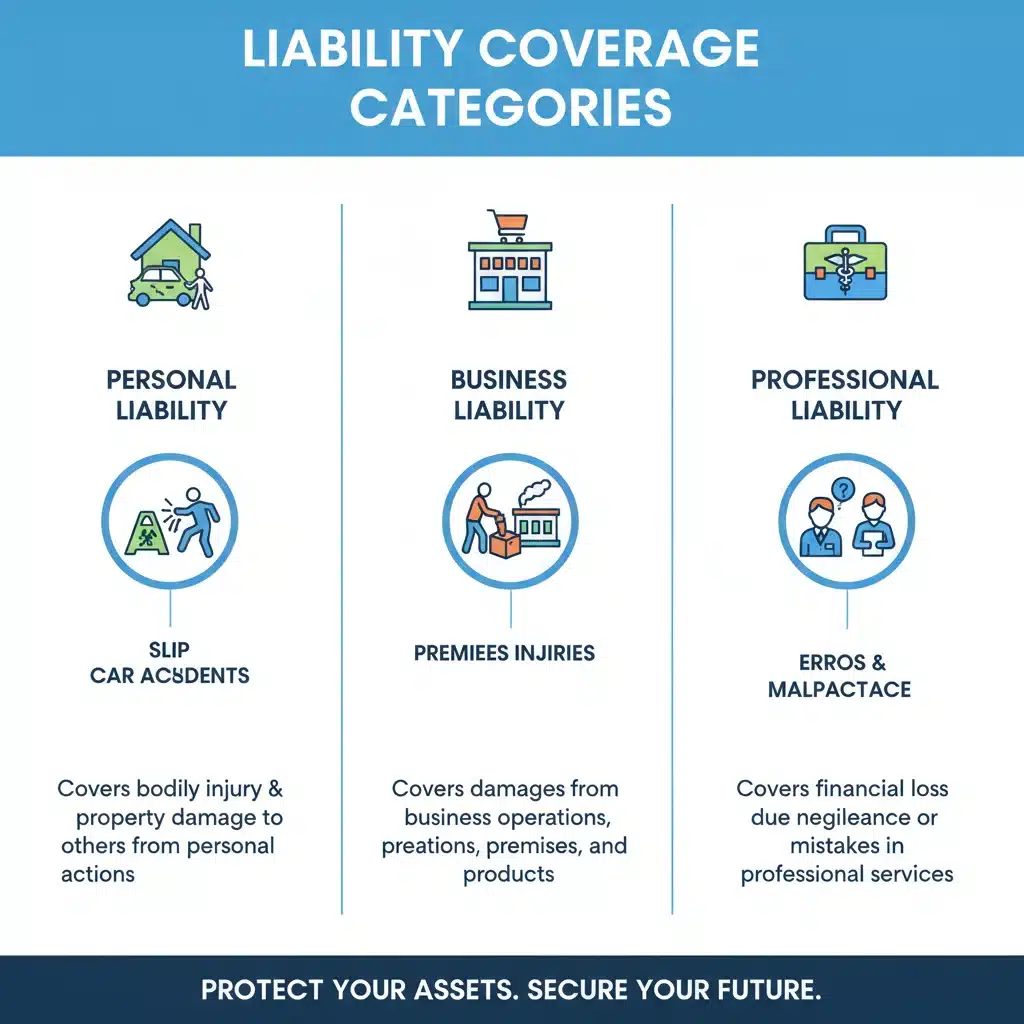
This is perhaps the most common form of liability protection, typically embedded within your homeowners or renters insurance policy. Personal liability insurance protects you and your household members against claims for bodily injury or property damage that you are legally responsible for. Imagine a guest tripping over a loose rug in your home and breaking an arm, or your child accidentally breaking a neighbor’s window with a baseball. These are scenarios where personal liability coverage would kick in. It covers medical expenses, legal fees, and settlement costs up to your policy limits. For those who own rental properties, landlord liability insurance provides similar protection against claims arising from your rental units.
Auto Liability Insurance
A mandatory requirement in most places, auto liability insurance is a critical component of liability coverage essentials for anyone who owns or operates a vehicle. It consists of two main parts: bodily injury liability and property damage liability. Bodily injury liability covers medical expenses, lost wages, and pain and suffering for others if you cause an accident. Property damage liability covers the cost of repairs to other vehicles or property that you damage in an accident. Without adequate auto liability, a serious accident could lead to immense out-of-pocket expenses, potentially bankrupting you.
Business Liability Insurance (Commercial General Liability – CGL)
For business owners, Commercial General Liability (CGL) insurance is non-negotiable. It protects your business from financial loss due to claims of bodily injury, property damage, advertising injury, and personal injury (e.g., libel or slander) caused by your business operations, products, or services. A customer slipping and falling in your store, a product you sell causing harm, or an employee damaging a client’s property are all scenarios covered by CGL. This coverage is a fundamental part of liability coverage essentials for any enterprise, regardless of size or industry, providing a crucial safety net against common business risks.
Professional Liability Insurance (Errors & Omissions – E&O)
Also known as Errors & Omissions (E&O) insurance, professional liability coverage is tailored for individuals and companies that provide professional services or advice. This includes doctors, lawyers, consultants, accountants, real estate agents, IT professionals, and many others. E&O insurance protects against claims of negligence, errors, or omissions in the professional services rendered. If a client sues you for financial loss due to a mistake in your professional advice or service, this policy would cover your legal defense costs and any damages awarded. It’s an indispensable aspect of liability coverage essentials for professionals whose livelihoods depend on their expertise and advice.
Umbrella Liability Insurance
An umbrella liability policy provides an extra layer of protection above and beyond the limits of your primary liability policies, such as homeowners, auto, and boat insurance. It kicks in when the liability limits of these underlying policies are exhausted. For example, if you’re involved in a severe car accident and the damages exceed your auto liability limits, your umbrella policy would cover the remainder, up to its own much higher limits (often starting at $1 million). This type of coverage is incredibly valuable for individuals with significant assets or those who face higher risk exposures, offering robust protection against catastrophic claims. It’s a key component of truly comprehensive liability coverage essentials.
Directors & Officers (D&O) Liability Insurance
For individuals serving on the board of directors or as officers of a company, D&O insurance is vital. It protects them personally from claims arising from their decisions and actions taken in their capacity as directors and officers. These claims can come from shareholders, employees, customers, or regulatory bodies, alleging mismanagement, breach of fiduciary duty, or other wrongful acts. D&O coverage ensures that personal assets of directors and officers are protected, making it a critical part of liability coverage essentials for corporate governance.
Why is Robust Liability Coverage More Important Than Ever in 2026?
The year 2026 brings with it a continuation of trends that underscore the increasing importance of robust liability coverage essentials. Several factors contribute to this heightened need for protection:
Rising Litigation and Award Amounts
There’s a noticeable trend towards increased litigation and higher jury awards in liability cases. This means that even seemingly minor incidents can escalate into costly legal battles, with potential settlements or judgments reaching astronomical figures. Without adequate liability limits, your personal and business assets could be severely exposed.
Evolving Digital Risks
The digital age introduces new forms of liability. Data breaches, cyberattacks, and privacy violations can lead to significant financial and reputational damage. While specialized cyber liability insurance addresses these specific risks, the general increase in digital footprint means that businesses and individuals face a broader spectrum of potential liabilities that might not have existed a decade ago. Understanding how these intersect with your existing liability coverage essentials is crucial.
Increased Regulatory Scrutiny
Governments and regulatory bodies are imposing stricter compliance requirements across various industries. Non-compliance can result in hefty fines and legal action, which liability policies can sometimes help mitigate, particularly D&O and E&O policies. The regulatory environment of 2026 demands meticulous attention to legal obligations and robust protection against the consequences of oversight.
Complex Business Operations
Modern businesses often operate across multiple jurisdictions, engage in complex supply chains, and utilize advanced technologies. Each of these elements introduces new layers of risk and potential liability. A comprehensive review of your liability coverage essentials should always consider the full scope of your business operations.
Personal Asset Growth
As individuals accumulate more assets – homes, investments, savings – the stakes of a liability claim become higher. A substantial judgment could wipe out years of financial planning and hard work. Umbrella insurance, in particular, becomes an indispensable tool for high-net-worth individuals to protect their accumulated wealth.
Choosing the Right Liability Coverage: Key Considerations for 2026
Selecting the appropriate liability coverage essentials requires careful consideration of your unique circumstances, risk exposures, and financial goals. Here’s a step-by-step approach to help you make informed decisions:
1. Assess Your Personal and Business Risks
Start by identifying all potential scenarios where you or your business could be held liable. For individuals, this includes property ownership (swimming pools, trampolines increase risk), vehicle usage, pets, and any part-time work or volunteer activities. For businesses, consider the nature of your operations, products/services, client interactions, employee count, and digital presence. A thorough risk assessment is the foundation for determining your liability coverage essentials.
2. Understand Your Current Policies
Review your existing insurance policies (homeowners, auto, business) to understand their current liability limits and exclusions. Many people are surprised to find their standard policies offer relatively low liability limits, which might be insufficient in today’s environment. Pay close attention to what is and isn’t covered. This will reveal gaps in your liability coverage essentials.
3. Determine Adequate Coverage Limits
Deciding on appropriate coverage limits is crucial. A common rule of thumb is to have liability coverage that at least matches your net worth, but often more is advisable, especially with rising court awards. Consider the potential severity of a claim. Could a catastrophic event lead to millions in damages? If so, an umbrella policy is likely a wise investment to bolster your liability coverage essentials.
4. Explore Specialized Coverage Options
Beyond the standard policies, investigate specialized liability coverages relevant to your situation. If you’re a professional, E&O insurance is non-negotiable. If you have a business, consider cyber liability, employment practices liability (EPLI), or even product liability if applicable. Each specialized policy fills a specific gap in your overall liability coverage essentials.
5. Consult with an Independent Insurance Agent
Navigating the complexities of liability insurance can be challenging. An experienced independent insurance agent can be an invaluable resource. They can help you assess your risks, compare policies from multiple carriers, and recommend the best combination of policies and limits to create a robust liability coverage essentials plan tailored to your needs. They can also explain jargon and help you understand the fine print.
6. Regularly Review and Update Your Policies
Life and business circumstances change, and so should your insurance coverage. Major life events like marriage, having children, buying a new home, starting a business, or acquiring significant assets should trigger a review of your liability coverage essentials. For businesses, growth, new products/services, or changes in operations necessitate a re-evaluation of coverage to ensure continued adequacy. Make it an annual habit to review your policies with your agent to confirm they still meet your needs for 2026 and beyond.
Common Misconceptions About Liability Coverage
Despite its importance, many individuals and businesses hold misconceptions about liability coverage essentials that can leave them dangerously exposed. Dispelling these myths is crucial for effective risk management:
Misconception 1: My Homeowners Policy Covers Everything
While homeowners insurance includes personal liability, it has limits. It typically won’t cover business-related liabilities, professional errors, or claims exceeding its specified maximums. Many people mistakenly believe this single policy is a catch-all, ignoring the need for separate business, professional, or umbrella coverage.
Misconception 2: I Don’t Have Enough Assets to Be Sued
This is a dangerous assumption. Even if you don’t have substantial current assets, a large judgment can garnish future wages, seize future inheritances, or force the sale of assets you acquire later. Furthermore, the cost of legal defense alone can be crippling, regardless of the outcome of a lawsuit. Liability coverage essentials protect your future financial capacity, not just your present assets.
Misconception 3: Liability Insurance is Too Expensive
The cost of liability insurance, especially an umbrella policy, is often surprisingly affordable when compared to the potential financial devastation of a major lawsuit. The peace of mind and financial protection it offers far outweigh the premium costs. Viewing it as an investment in your financial security rather than an expense can shift this perspective.
Misconception 4: My Business is Too Small to Need CGL or E&O
No business is too small to face a liability claim. A sole proprietor working from home can still be sued if a client is injured on their premises or if their professional advice leads to financial loss. In fact, small businesses often have fewer resources to absorb legal costs, making robust liability coverage essentials even more critical for them.
The Future of Liability: Trends to Watch in 2026 and Beyond
As we look ahead, several trends are poised to shape the future of liability coverage essentials. Staying abreast of these developments will help you anticipate future risks and adapt your protection strategies accordingly:
AI and Automation-Related Liabilities
The increasing integration of Artificial Intelligence (AI) and automation across industries introduces complex liability questions. Who is responsible when an AI system makes an error that causes harm? Manufacturers, developers, or users? New forms of liability insurance are emerging to address these novel risks.
Climate Change and Environmental Liabilities
As climate change impacts intensify, businesses and property owners may face increased liability risks related to environmental damage, pollution, or failure to adapt to new climate regulations. This will likely necessitate a closer look at environmental liability components within liability coverage essentials.
Social Inflation
The term ‘social inflation’ refers to the rising costs of insurance claims due to factors like increased litigation, larger jury awards, and broader interpretations of liability. This trend puts upward pressure on insurance premiums and underscores the need for higher coverage limits.
Gig Economy and Contractor Liabilities
The growth of the gig economy means more individuals are working as independent contractors. The lines of liability between platforms, contractors, and clients can be blurred, requiring careful consideration of specialized liability coverage for gig workers and the platforms that employ them.
Conclusion: Prioritizing Your Liability Coverage Essentials for a Secure 2026
In conclusion, understanding and proactively managing your liability coverage essentials is fundamental to protecting your financial well-being in 2026 and for years to come. The world is full of uncertainties, and while we can’t predict every challenge, we can certainly prepare for them. By taking the time to assess your risks, understand the various types of liability insurance available, and work with knowledgeable professionals, you can build a robust defense against potential claims.
Don’t wait for an unfortunate event to discover gaps in your coverage. Be proactive. Review your policies annually, adjust your limits as your life or business evolves, and always prioritize comprehensive protection. Investing in adequate liability coverage isn’t just about complying with legal requirements; it’s about investing in peace of mind, safeguarding your assets, and securing your future against the unexpected. Make 2026 the year you master your liability coverage and fortify your financial fortress.