In the complex world of insurance, understanding your coverage is paramount. Yet, for many, the thick binder of policy documents remains largely unread, save for the initial signing. Among these crucial papers, one stands out as the most vital summary of your protection: the policy declarations page. Often overlooked, this single page (or a few pages) is your quick reference guide to what’s covered, for how much, and under what conditions. As we move into 2026, the landscape of insurance continues to evolve, making a thorough understanding of your declarations page more important than ever.
This comprehensive guide will walk you through every essential section of your policy declarations page, explaining its significance and offering actionable advice on what to look for. By the end, you’ll be equipped to not only read but truly comprehend your insurance policy, ensuring your coverage aligns perfectly with your needs and expectations. Don’t let uncertainty leave you vulnerable; empower yourself with knowledge.
The policy declarations page, often simply called the ‘dec page,’ is the front-facing summary of your insurance contract. It’s designed to provide a concise overview of the most critical aspects of your policy without requiring you to sift through pages of legal jargon. Think of it as the executive summary of your insurance agreement. While the full policy document contains all the terms, conditions, exclusions, and definitions, the declarations page distills the key information you need to know at a glance.
The Indispensable Role of Your Policy Declarations Page
Why is the policy declarations page so important? Firstly, it serves as proof of insurance. Whether you’re registering a vehicle, applying for a mortgage, or simply need to demonstrate coverage, this page is usually what you’ll present. Secondly, and more critically, it outlines the financial specifics of your coverage. It tells you your coverage limits, deductibles, premiums, and the policy period. Without understanding these elements, you could unknowingly be underinsured, overpaying, or simply confused about what to expect in the event of a claim.
Regularly reviewing your policy declarations page is not just a good practice; it’s a necessity, especially with life changes or policy renewals. Your needs evolve, and so should your insurance. A change in marital status, the purchase of a new asset, or even a move to a new location can significantly impact your insurance requirements. A yearly review, particularly around renewal time, ensures that your policy remains accurate and adequate for your current situation.
Key Sections to Scrutinize on Your Policy Declarations Page in 2026
Let’s break down the essential components you’ll find on your policy declarations page and what each means for your coverage. Understanding these sections is fundamental to ensuring you have the right protection.
1. Policy Number and Period
This section is straightforward but crucial. The policy number is a unique identifier for your specific insurance contract. You’ll need it for any communication with your insurer, whether it’s making a claim, asking a question, or paying your premium. The policy period indicates the start and end dates of your coverage. It’s essential to note these dates to ensure there are no gaps in your protection. A lapse in coverage, even for a day, can leave you completely exposed in the event of an incident.
2. Named Insured(s) and Additional Insureds
The ‘named insured(s)’ are the individuals or entities legally covered by the policy. For personal policies, this typically includes you and possibly your spouse or other household members. For business policies, it would be the business entity. ‘Additional insureds’ are other parties who may have an insurable interest and are added to the policy, often through an endorsement. For example, a landlord might be an additional insured on a tenant’s renter’s policy. Always verify that all relevant parties who need coverage are accurately listed.
3. Insured Property or Vehicle Description
This section details what is being insured. For auto insurance, it will list the year, make, model, and Vehicle Identification Number (VIN) of each vehicle covered. For homeowners insurance, it will include the property address. If you have a personal articles policy, it will list the specific items (e.g., jewelry, art) and their appraised values. Double-check these descriptions for accuracy. An incorrect VIN or address could lead to significant issues during a claim.
4. Coverage Types and Limits
This is arguably the most critical section of your policy declarations page. It outlines the specific types of coverage you have and the maximum amount the insurer will pay for a covered loss (the ‘limit’).
- Liability Coverage: Protects you if you’re found legally responsible for bodily injury or property damage to others. For auto, this is often split into bodily injury per person, bodily injury per accident, and property damage. For homeowners, it covers incidents occurring on your property.
- Property Coverage: For homeowners, this covers the dwelling itself, other structures (like a detached garage), and personal property. For auto, it includes collision (damage to your car from an accident) and comprehensive (damage to your car from non-collision events like theft, vandalism, or natural disasters).
- Medical Payments/Personal Injury Protection (PIP): Covers medical expenses for you and your passengers, regardless of fault, up to a certain limit.
- Uninsured/Underinsured Motorist (UM/UIM): Protects you if you’re hit by a driver who has no insurance or insufficient insurance to cover your damages.
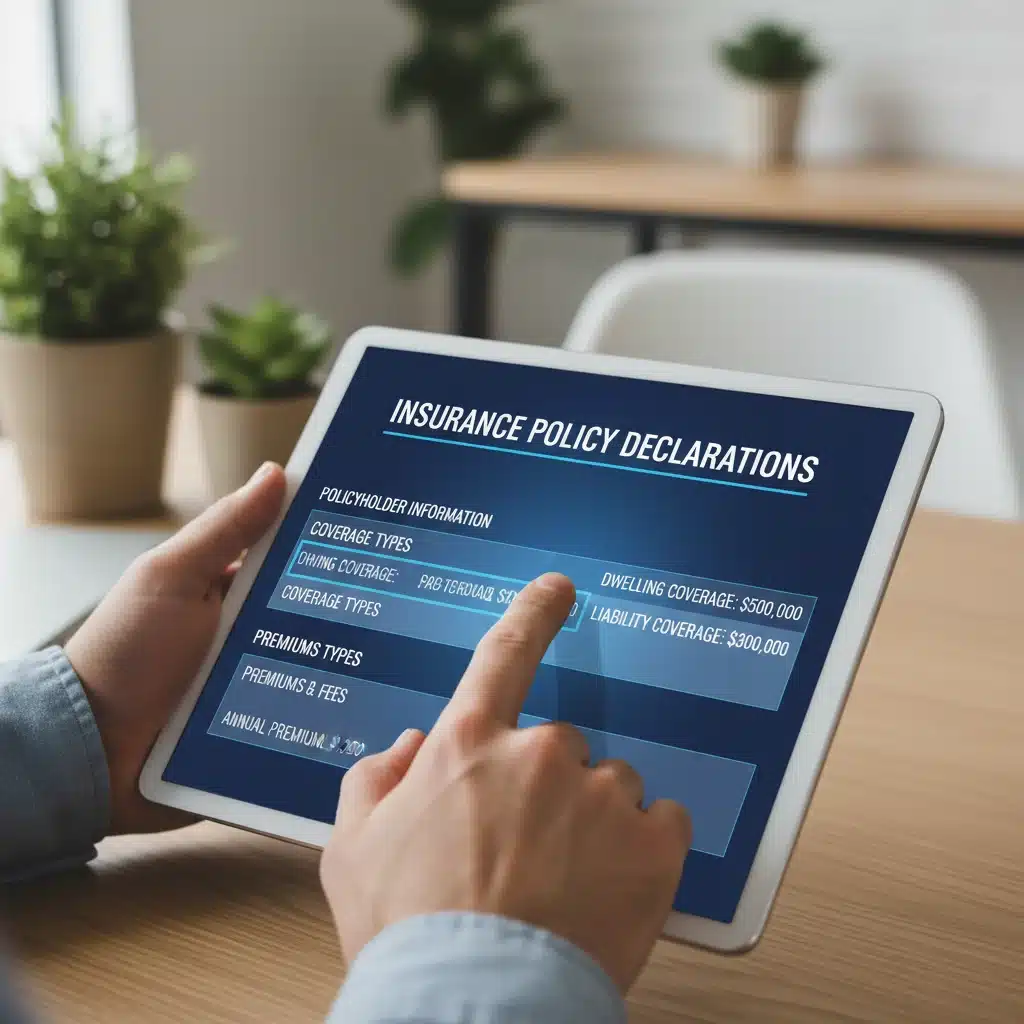
Each of these coverage types will have a corresponding limit. It’s crucial to review these limits carefully. Are they sufficient to protect your assets? For example, if your home is valued at $500,000, but your dwelling coverage limit is only $300,000, you are significantly underinsured. Similarly, low liability limits could leave your personal assets exposed in a major lawsuit.
5. Deductibles
A deductible is the amount you must pay out-of-pocket before your insurance coverage kicks in. For example, if you have a $1,000 deductible on your home insurance and suffer $10,000 in damage, you would pay the first $1,000, and your insurer would cover the remaining $9,000. Deductibles vary by coverage type (e.g., collision, comprehensive, hurricane, wind/hail). Higher deductibles typically lead to lower premiums, but they also mean a greater out-of-pocket expense at the time of a claim. Ensure your deductibles are amounts you can comfortably afford to pay if a loss occurs.
6. Premiums and Payment Schedule
This section details the cost of your insurance policy for the specified period and how often you need to pay it (e.g., monthly, quarterly, annually). It will also typically show any discounts applied. Compare your premium against previous periods or quotes from other insurers. If you notice a significant increase, it’s worth investigating why. Discounts for things like good driving, bundling policies, or home security systems should be reflected here. If you believe you qualify for a discount that isn’t listed, contact your insurer.
7. Endorsements and Exclusions
The policy declarations page will often list any endorsements (also known as riders or add-ons) that modify your standard policy. Endorsements add or remove coverage for specific situations. For example, a scheduled personal property endorsement adds extra coverage for high-value items not fully covered by standard personal property limits. Conversely, it might also list specific exclusions that limit coverage. For example, a homeowners policy in a flood-prone area might explicitly exclude flood damage unless a separate flood insurance policy is purchased. Carefully review these to understand any deviations from standard coverage.
8. Mortgagee/Lienholder Information
If you have a loan on your property or vehicle, the lender (mortgagee for real estate, lienholder for vehicles) will be listed here. They have an insurable interest in your asset, and your insurer will typically notify them of any policy changes or cancellations. This ensures their investment is protected. Verify that the correct lender and their contact information are listed.
Why a 2026 Review of Your Policy Declarations Page is Critical
The year 2026 brings its own set of considerations for insurance policyholders. The insurance industry is constantly adapting to new risks, technological advancements, and regulatory changes. Here’s why a focused review of your policy declarations page is more important than ever:
- Inflation and Rising Costs: Construction costs, vehicle repair costs, and medical expenses continue to rise. Your current coverage limits from a few years ago might no longer be adequate to fully replace your home or car, or cover extensive medical bills. Revisit your dwelling coverage limits and personal property limits to ensure they reflect current market values.
- Climate Change Impacts: Weather patterns are becoming more extreme and unpredictable. If you live in an area prone to specific natural disasters (e.g., wildfires, hurricanes, floods, tornadoes), ensure your endorsements and exclusions adequately address these risks. You might need to consider separate policies (like flood insurance) if your standard policy excludes them.
- Technological Advancements: New smart home devices can offer discounts, but they also introduce new vulnerabilities. Similarly, advanced driver-assistance systems in cars can impact repair costs and liability. Discuss these with your agent to see how they affect your policy and potential discounts.
- Increased Liability Risks: Social inflation (the rising costs of insurance claims due to increased litigation, larger jury awards, and higher medical costs) means higher liability limits are becoming increasingly important to protect your assets.
- Personal Life Changes: Did you get married, have a child, buy a new car, renovate your home, or start a home-based business? All these events necessitate a review of your coverage. Your policy declarations page should always reflect your current life situation.
Actionable Steps for Reviewing Your Policy Declarations Page
Now that you understand the different sections, here’s how to effectively review your policy declarations page:
- Locate Your Latest Page: Always use the most current declarations page. If you receive policy documents via mail or email, ensure you’re looking at the latest version for your current policy period.
- Compare Against Your Needs: Go through each section and compare what’s listed against your current assets, liabilities, and risk tolerance. Ask yourself:
- Are all my vehicles/properties accurately described?
- Are all individuals who need coverage listed as named or additional insureds?
- Are my coverage limits high enough to replace my assets or protect me from potential lawsuits?
- Can I afford my deductibles in an emergency?
- Are there any exclusions that leave me vulnerable to risks I face?
- Am I receiving all applicable discounts?
- Understand the Jargon: If you encounter terms you don’t understand, don’t guess. Look them up in your full policy document’s definitions section or, better yet, ask your insurance agent.
- Document Discrepancies: Make notes of anything that seems incorrect, outdated, or unclear.
- Contact Your Agent/Insurer: Schedule a meeting or call with your insurance agent or a company representative. Discuss your findings and ask for clarification on any confusing points. This is also the time to request adjustments to your coverage if your needs have changed.
- Keep Records: Once you’ve reviewed and made any necessary changes, save a copy of your updated policy declarations page in a safe and accessible place, both physically and digitally.
The Role of Your Insurance Agent
Your insurance agent is an invaluable resource in this process. They can help you interpret the complex language of your policy, explain the implications of different coverage limits and deductibles, and recommend adjustments based on your specific circumstances. Don’t hesitate to lean on their expertise. A good agent will proactively reach out for annual reviews, but if they don’t, take the initiative yourself.
Common Pitfalls to Avoid
- Assuming Coverage: Never assume something is covered just because you have insurance. The policy declarations page and the full policy document are the ultimate authorities.
- Ignoring Renewal Notices: Renewal notices often come with an updated declarations page. This is your prime opportunity to review and make changes before the new policy period begins.
- Focusing Only on Price: While premiums are important, don’t sacrifice adequate coverage for a lower price. An insufficient policy can cost you far more in the long run.
- Not Updating Information: Failing to inform your insurer of significant life changes (e.g., new address, new driver, home renovation) can lead to coverage denials or insufficient payouts.
Conclusion: Empowering Yourself Through Knowledge
Your policy declarations page is more than just a piece of paper; it’s a critical financial document that outlines your protection against life’s uncertainties. In 2026, with an evolving risk landscape and economic shifts, taking the time to thoroughly review and understand this page is an act of financial prudence. By meticulously checking your policy number, insured parties, property descriptions, coverage limits, deductibles, premiums, and any endorsements or exclusions, you empower yourself to make informed decisions about your insurance.
Don’t wait for a claim to discover gaps in your coverage. Proactive review of your policy declarations page ensures that your insurance truly serves its purpose: providing peace of mind and robust financial protection when you need it most. Make it an annual habit, engage with your insurance agent, and stay informed – your future self will thank you for it.